
Key takeaways
- CAM reconciliation compares a tenant’s estimated payments with its share of recoverable expenses for the period. The lease determines which costs can be billed and how they are allocated.
- An occupancy gross-up generally adjusts eligible variable expenses. Fixed costs, such as property taxes, should not be increased simply because space is vacant.
- The order of a cap and gross-up can change the result. Both the calculation sequence and the cap’s base amount need to follow the lease.
- Statement delivery, payment, objections and audits may have separate deadlines. Record each requirement and retain the supporting documents.
A tenant has paid $18,000 a month toward operating expenses. At year-end, the property manager must determine whether those $216,000 of payments covered the tenant’s contractual share. That requires matching the accounting records to the tenant’s lease.
In the hypothetical Harbor Court example below, the correct annual charge is $316,266. Ignoring an expense cap, grossing up fixed costs and using the wrong square-footage denominator increases it to $445,313. The example shows how individual lease terms affect a reconciliation.
Tenants in the same building may have different exclusions, expense stops and caps. A building-wide expense schedule is a useful starting point, but each tenant’s calculation needs to reflect its agreement.
This guide explains the calculation, walks through the example and outlines the records needed to review a year-end statement.
What is CAM reconciliation?
A CAM reconciliation is the year-end (sometimes quarterly) comparison of estimated common-area charges billed during the period against the tenant’s share of actual recoverable expenses, so a shortfall is a true-up and an overage is a credit.
Reconciliation can appear in net and modified-gross leases, as well as full-service arrangements with a base year or expense stop. In a triple-net lease, taxes, insurance and maintenance may be billed separately or reconciled through an operating-expense statement. The lease’s payment provisions determine the process.
Recoverable expenses are the costs included by the lease, after its exclusions and adjustments. When tenants pay estimated CAM charges, reconciliation compares those payments with the final recoverable amount. Some leases instead set fixed charges or other arrangements that do not require the same true-up.
Axios reported the Seattle region’s office vacancy rate at 17.3% in December 2025. Vacancy makes the treatment of occupancy-sensitive expenses especially relevant. A regional vacancy figure cannot supply the gross-up factor for an individual property: the calculation needs that building’s occupancy data and the adjustment permitted by each lease.
The four terms the lease has to answer
A tenant’s percentage is only one input. Review these four provisions before applying it to the expense schedule.
1. What is in the pool?
Identify included operating costs, excluded charges and any capital expenditures the lease permits the landlord to recover through amortization. A repair and a replacement may receive different treatment. The University of California leasing guide recommends negotiating limits on capital-cost pass-throughs; that guidance reflects the university’s tenant position, rather than a rule for every commercial lease.
2. What is the denominator?
Use the area and measurement convention specified in the lease. Dividing tenant rentable square feet by total building rentable square feet produces a different share from dividing by occupied space. The UC guide specifically flags occupied-space allocation as an issue to check against the contract. Confirm how additions, remeasurement and excluded areas affect the calculation.
3. Does variable expense get grossed up, and to what occupancy?
A gross-up estimates eligible variable expenses at a stated occupancy level. Apply it only to the portion of a cost that changes with occupancy and that the lease allows to be adjusted. A utility account, for example, can contain both fixed and variable charges. Property taxes and insurance ordinarily do not decline proportionately when a suite becomes vacant.
The Texas A&M University System’s Century Square office lease illustrates a contract with a 100% occupancy adjustment. The Harbor Court example uses 95%. Neither percentage is a universal standard.
4. Is there a cap, and in what order?
A controllable-expense cap limits increases in the categories defined as controllable by the lease. Check whether it is cumulative, whether unused increases carry forward, and which base amount applies. Also establish whether the cap applies before or after gross-up. Those details determine the permitted charge.
Review audit rights alongside the calculation provisions. The UC standard form lease, for example, gives the tenant access to verify passed-through expenses. Another lease may specify a request window, permitted reviewers and limits on audit costs.
Record the event that starts each deadline. It may be receipt of a statement, supporting records or both. Retention requirements also vary: a Texas A&M System lease form requires relevant books to be kept for seven years after expiration.
Worked CAM reconciliation example
Assume Harbor Court has 100,000 rentable square feet, with 80,000 occupied during the reconciliation period. Tenant A occupies 25,000 square feet. All amounts below are hypothetical and rounded to the nearest dollar after calculation.
Tenant A’s lease assigns 25% of building expenses, permits eligible variable costs to be grossed up to 95% occupancy, and excludes capital improvements. For this first annual cap adjustment, the controllable-expense base is $380,000 and the permitted increase is 5%, applied before gross-up. The tenant paid $216,000 in estimates. This example assumes no other stops, caps or adjustments.
The expense schedule distinguishes the variable pool from its controllable subset, so the subset is not counted twice:
| Category | Amount | Gross-up | Cap |
| Eligible occupancy-sensitive service costs | $480,000 | Yes, to 95% | Controllable subset, yes |
| Fixed (real-estate tax, insurance) | $720,000 | No | No |
| Controllable subset of variable | $420,000 | After the cap | Cap base: $380,000 |
| HVAC replacement (capital) | $60,000, already removed | No | No |
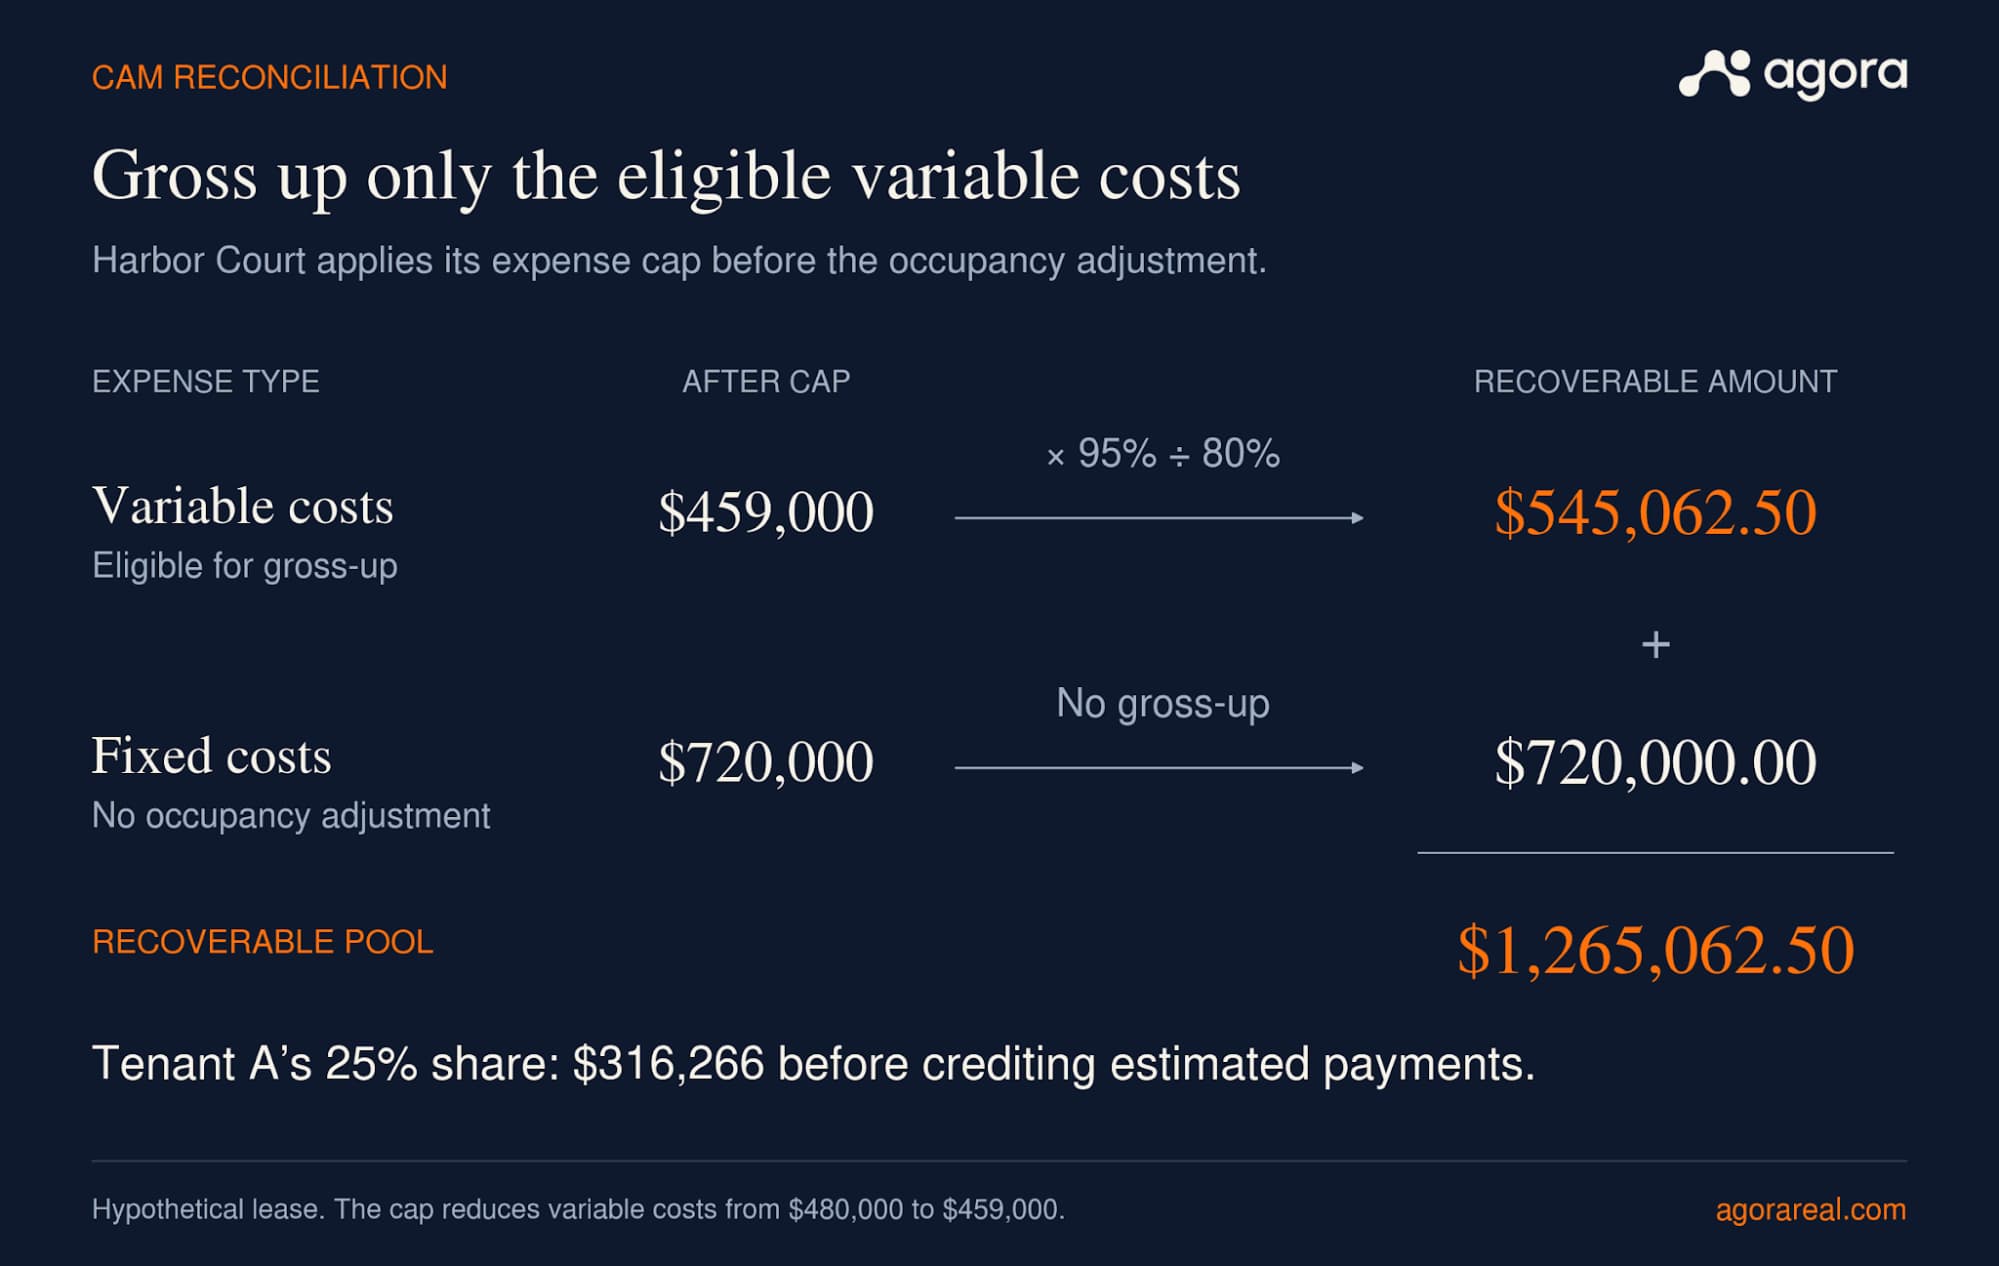
Apply the cap: $380,000 × 1.05 = $399,000. Actual controllable expenses of $420,000 exceed that ceiling by $21,000. Remove the excess from the $480,000 variable pool, leaving $459,000.
Gross up the remaining eligible variable expenses: $459,000 × (95% ÷ 80%) = $545,062.50.
Add fixed recoverable expenses: $545,062.50 + $720,000 = $1,265,062.50.
Apply Tenant A’s share and subtract estimates: ($1,265,062.50 × 25%) − $216,000 = $100,265.63, or a $100,266 true-up. The total annual charge is $316,266 when rounded.
Changing individual inputs shows why the lease review matters:
| Calculation scenario | Tenant share | True-up billed | Versus the lease |
| Lease applied correctly | $316,266 | $100,266 | Base |
| Gross-up applied to tax and insurance as well | $350,016 | $134,016 | +$33,750 |
| Cap ignored | $322,500 | $106,500 | +$6,234 |
| Occupied RSF used as the denominator (25,000 / 80,000) | $395,332 | $179,332 | +$79,066 |
| All three mistakes at once | $445,313 | $229,313 | +$129,047 |

The combined-error row ignores the cap, grosses up the fixed expense pool and uses occupied square feet as the denominator. The $60,000 capital replacement remains excluded in every scenario. Together, those three errors overstate Tenant A’s annual charge by $129,047.
How a CAM error becomes a valuation error
An incorrect recovery can distort the price paid for a property. In a separate hypothetical acquisition, assume unsupported recurring CAM billings overstate sustainable annual NOI by $25,000. Capitalizing that income at 6% overstates indicated value by about $417,000 ($25,000 ÷ 0.06). A one-time billing difference should not be treated as a recurring income stream.
Before using trailing NOI to price a deal, reconcile recoveries to the leases and the expense ledger. Remove amounts that cannot be supported or sustained, then recalculate value. CAM review belongs in acquisition due diligence as well as the year-end accounting process.
Cap order and reconciliation deadlines
The sequence of adjustments deserves its own check because changing it can alter the amount recoverable even when every invoice is correct.
Harbor Court caps actual controllable expenses at $399,000 before gross-up. That reduces the variable pool to $459,000 and produces Tenant A’s $316,266 annual charge.
For comparison, assume a different lease applies the same $399,000 ceiling after gross-up. The $480,000 variable pool becomes $570,000, and its $420,000 controllable subset becomes $498,750. Removing the $99,750 above the cap leaves $470,250 of variable expenses. Adding $720,000 of fixed expenses and taking 25% produces a $297,563 annual charge.
The difference is $18,703 under these stated assumptions. A real lease may also adjust the cap base, so confirm both the sequence and the basis of comparison before using either formula.
Delivery deadlines can affect recovery, but their consequences depend on the contract and applicable law. In Brookhill Capital Resources v. Jalensky Sports Center, a Wisconsin appeals court considered late CAM statements and disputed parking-lot resurfacing costs.
The court did not treat a stated billing deadline as an automatic bar to collection. It found factual issues about whether timely delivery was essential to the agreements and ambiguity over the resurfacing charges. The practical lesson is to document deadlines and clarify capital-cost treatment before a dispute arises.
In Mount Sinai Hospital v. 1998 Alexander Karten Annuity Trust, the landlord sent more than a decade of additional-rent statements together. Applying that lease’s billing provisions, the New York appellate court allowed recovery for 2009 and 2010 but barred the earlier years.
These decisions concern their own agreements and facts. They do not establish a single national CAM billing or audit deadline.
The Century Square agreement takes another approach: it provides for a statement within 120 days after year-end, payment or credit within 30 days of the statement, and continuing tenant obligations despite late delivery. Keep evidence of when statements and supporting records were sent and received.
If a statement changes, identify the revised version, explain the adjustment and retain the earlier version. Property accounting and NOI reporting should use the approved reconciliation consistently.
What a CAM reconciliation statement should show
A useful statement gives the tenant enough detail to follow the calculation and request supporting records. Include:
- Recoverable pool by category (tax, insurance, utilities, janitorial, repairs, management), with the general-ledger total, the exclusions removed, and capital items listed by name.
- The controllable-expense categories, cap base, permitted increase and amount excluded by the cap.
- Gross-up calculation: the occupancy, the lease names, actual occupancy, and the factor applied (here 0.95 / 0.80), applied to variable accounts only.
- Denominator: building RSF or occupied RSF, per the lease, and the tenant’s resulting share.
- Estimates billed for the period, the true-up or credit, and the due date the lease sets.
- Statement delivery details, payment deadline and the lease’s objection or audit requirements.
For a tenant review, compare exclusions, caps, occupancy adjustments and allocation against the lease before checking the arithmetic. Apply the steps in the contractual order and record any assumptions that need clarification.
Maintain a complete reconciliation record
Keep a lease abstract that captures the expense definitions and calculation rules, with references to the relevant clauses and amendments. The abstract should support review of the signed lease rather than replace it.
Store the approved statement with its expense schedule, invoices, occupancy support, correspondence and delivery evidence. Accurate recovery records help explain changes in NOI and cash available for investor distributions.
Agora’s document management tools help teams organize agreements, reports and other records by investment. Keeping the supporting CAM record accessible makes it easier to explain an operating-income adjustment when preparing investor communications.
Conclusion
A reliable CAM reconciliation connects the recoverable expense schedule to each tenant’s lease and estimated payments. Clear treatment of exclusions, occupancy, allocation and caps makes the resulting true-up easier to review.
Before sending the statement, verify its calculation and delivery requirements. Preserve the supporting records so questions can be answered without rebuilding the analysis.