Key takeaways
- The taxable gain on a sale depends on an adjusted basis, including depreciation, as well as the amount realized. The loan payoff affects cash proceeds separately.
- Long-term capital gains may qualify for 0%, 15%, or 20% federal rates. Depreciation-related gain can receive different treatment, including a maximum 25% rate on unrecaptured section 1250 gain.
- The 3.8% net investment income tax may also apply. State taxes and the owner’s circumstances can change the total liability.
- A qualifying 1031 exchange can defer gain, subject to strict requirements. In a partnership-owned property, each investor generally reports their allocated share of taxable results.
Selling a depreciated commercial property can create a larger taxable gain than the change in its purchase price suggests. Depreciation reduces the property’s tax basis, and different portions of the gain may be taxed at different rates.
For example, the $5 million sale below produces a $2.4 million gain and an illustrative federal liability of $626,200 under the stated assumptions. Working through the basis and tax categories explains how that amount is calculated.
This guide covers the 2026 federal rate thresholds, depreciation-related gain, common deferral options, and partnership reporting. Use the framework to prepare an exit estimate with the CPA or tax counsel responsible for the transaction.
What gain means on a commercial sale
Gain is the amount realized minus adjusted basis. Publication 544 defines the amount realized as cash plus the fair market value of other property received, plus liabilities the buyer assumes, minus selling expenses.
Adjusted basis starts with cost. Publication 551 adds capital improvements and subtracts depreciation allowed or allowable. That last reduction is why a fully depreciated building can still produce a large tax bill on a modest cash exit.
Reconcile the original cost, improvement schedule, and depreciation records before estimating the gain. Debt repayment reduces the cash available at closing but does not itself reduce taxable gain.
2026 capital gains rates and additional federal taxes
The following taxable-income thresholds come from IRS Revenue Procedure 2025-32. They apply to the regular 0%, 15%, and 20% long-term capital gains bands for tax years beginning in 2026.
| Filing status | Taxable income up to this amount: 0% band | Upper taxable-income limit of the 15% band |
| Married filing jointly / surviving spouse | $98,900 | $613,700 |
| Married filing separately | $49,450 | $306,850 |
| Head of household | $66,200 | $579,600 |
| All other individuals (including single) | $49,450 | $545,500 |
| Estates and trusts | $3,300 | $16,250 |
The 20% band applies above the second threshold. Gains are considered alongside other taxable income, so different portions can fall in different bands. These thresholds do not make all depreciation-related gain eligible for the same rates.
For depreciable real estate, part of a long-term gain may be unrecaptured section 1250 gain. IRS Topic 409 identifies a maximum 25% rate for that portion; the actual rate depends on the taxpayer’s calculation.
Sales of business property may first be reported on Form 4797. Section 1231 netting and its five-year loss lookback can affect whether gain receives capital-gain treatment. The simplified example below assumes no loss-lookback recharacterization or offsetting losses.
For many buildings depreciated using straight-line depreciation, ordinary-income recapture under section 1250 is limited or absent. Unrecaptured section 1250 gain can still apply. These are distinct tax categories.
The net investment income tax is 3.8% of the lesser of net investment income or modified adjusted gross income above the applicable threshold: $250,000 for joint filers, $125,000 for married filing separately and $200,000 for single or head-of-household filers. Whether property-sale gain is included depends in part on the trade-or-business and participation rules.
Model state and local taxes separately, including the rules where the property is located and where its owners file returns. Federal treatment does not determine the full tax cost.
Worked example: A $5 million commercial property sale
This hypothetical example assumes a U.S. individual owner and a fully taxable sale. It isolates the federal taxes on the gain; it is not an estimate for a named property or investor.
The property sells for $5 million, including any amount used to repay its mortgage. Selling expenses of $200,000 leave $4.8 million realized. Original basis of $3.2 million plus $300,000 of improvements, less $1.1 million of allowed or allowable straight-line building depreciation, produces an adjusted basis of $2.4 million. The resulting gain is $2.4 million.

Assume a holding period longer than one year, no section 1245 assets, and sufficient other taxable income for the full $1.1 million depreciation-related portion to bear 25% and the remaining $1.3 million to bear 20%. Also assume all gain is net investment income and the MAGI excess is large enough for NIIT to apply to the full gain. Exclude credits, losses and state taxes.
| Layer | Amount | Rate in this example | Federal tax on layer |
| Unrecaptured section 1250 (depreciation taken) | $1,100,000 | 25% maximum | $275,000 |
| Remaining long-term capital gain | $1,300,000 | 20% | $260,000 |
| Subtotal before NIIT | $2,400,000 | $535,000 | |
| NIIT on the gain (simplified) | $2,400,000 | 3.8% | $91,200 |
| Illustrative federal total | $626,200 |
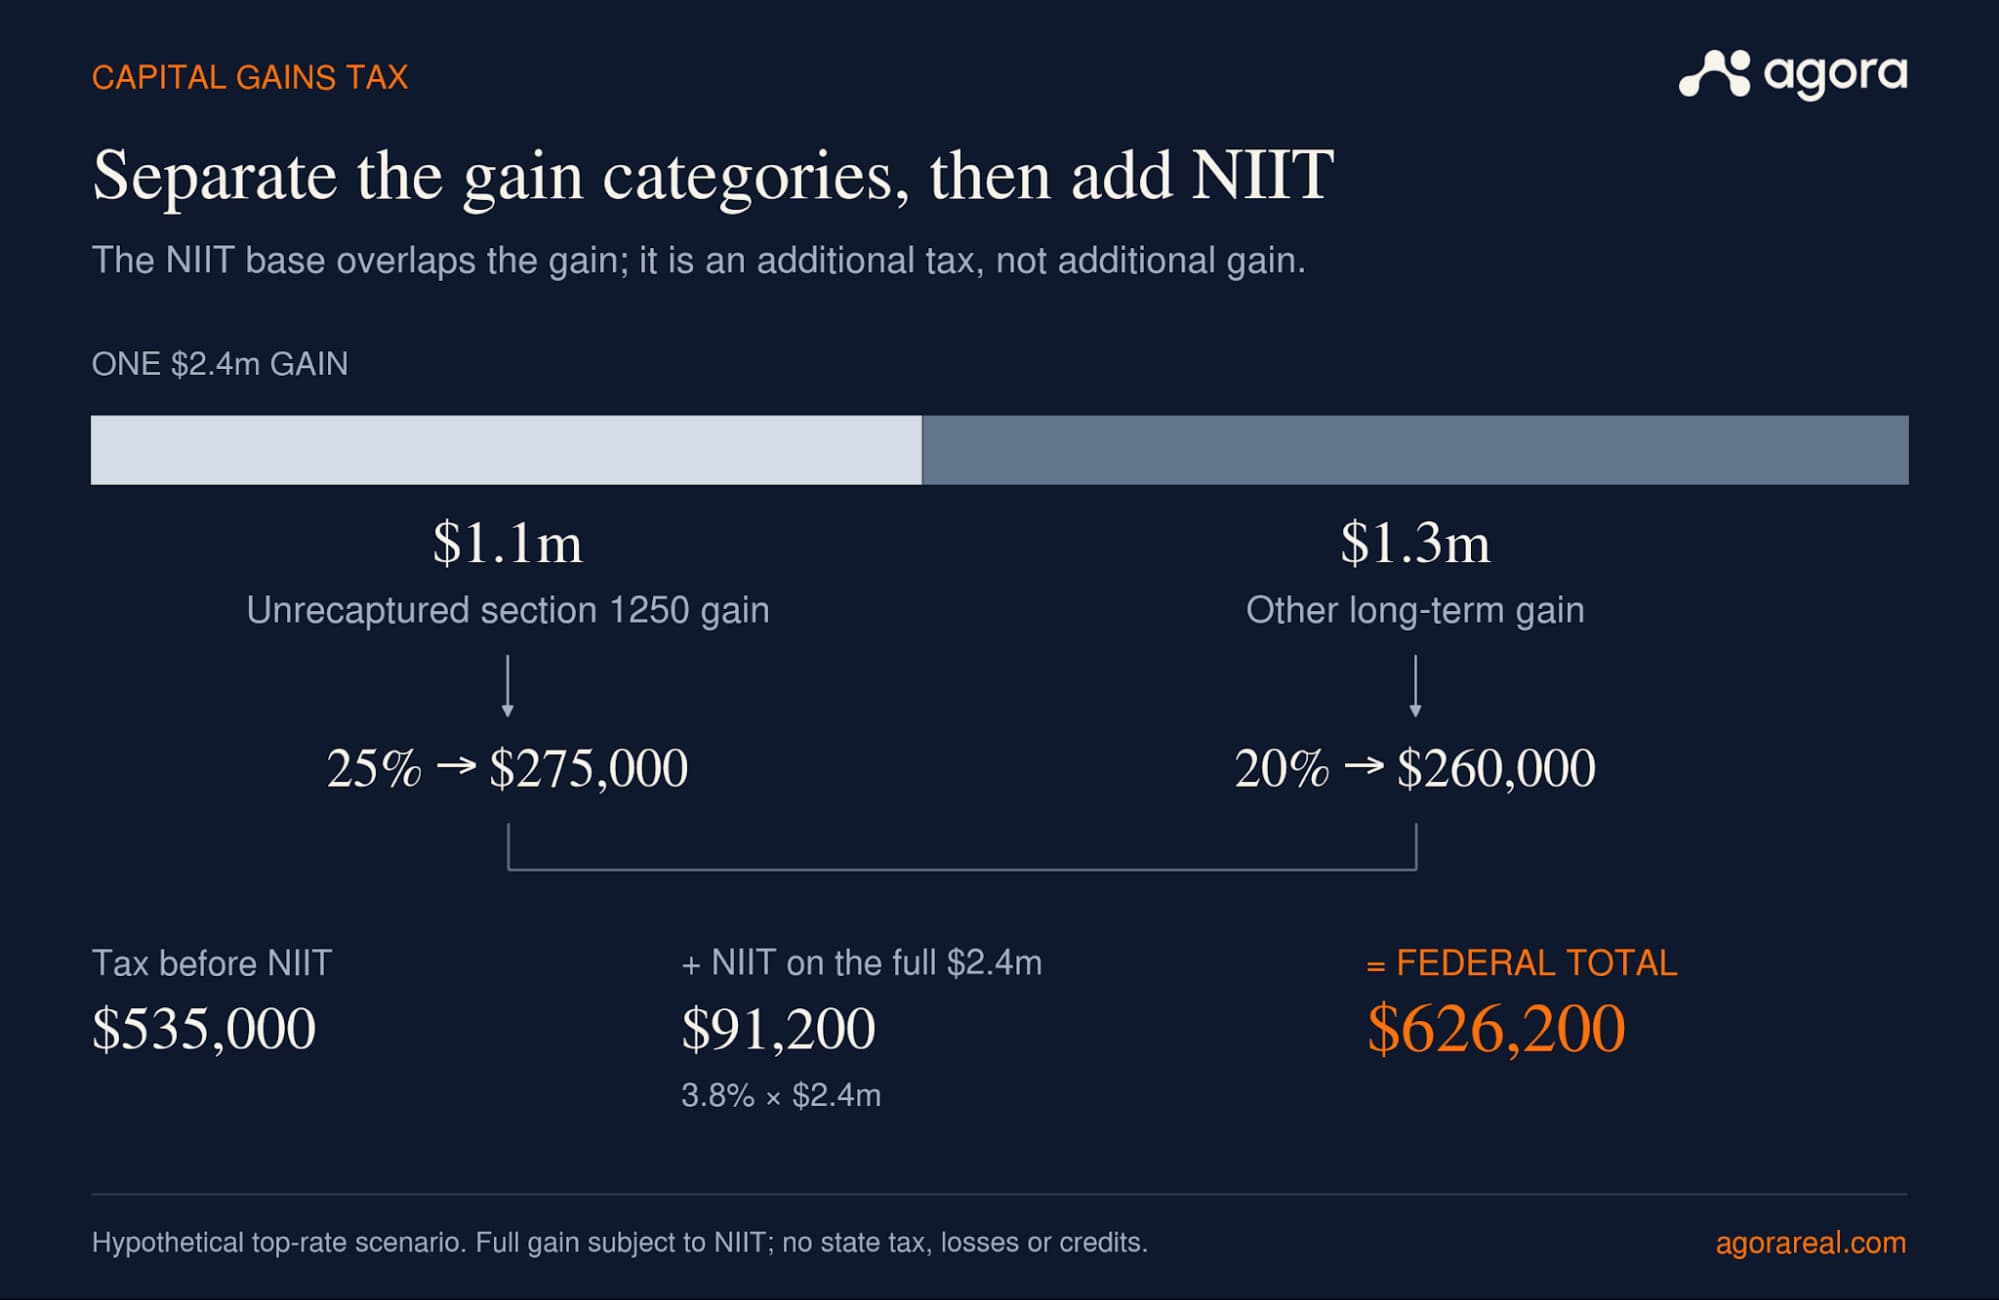
Applying only 20% to the $2.4 million gain would estimate $480,000. Under these assumptions, the additional depreciation-related tax and NIIT increase the federal estimate by $146,200.
Lower taxable income, losses or an exception to NIIT can change the result. The maximum 25% rate on unrecaptured section 1250 gain is not a fixed rate for every investor.
If an LLC taxed as a partnership owns the property, taxable gain and its character are allocated to partners under the applicable tax rules and reported on Schedule K-1. Each investor applies their own tax circumstances to the allocated amount.
Section 1245 recapture on segregated components
A cost-segregation study identifies components with different tax classifications and recovery periods. Some qualify as section 1245 personal property, while certain improvements remain section 1250 property. A 5-, 7- or 15-year recovery period alone does not establish the recapture category. The IRS cost-segregation audit guide discusses these distinctions.
For section 1245 property sold at a gain, ordinary-income recapture generally applies up to prior depreciation, subject to the gain limitation and applicable rules. For section 1250 property, additional depreciation and unrecaptured gain require separate analysis. Allocate the sale price and basis to the relevant assets before calculating these amounts.
For illustration, suppose $300,000 of gain otherwise modeled at 25% is properly classified as section 1245 recapture and the owner’s marginal ordinary rate is 37%. Tax on that portion becomes $111,000 instead of $75,000, a $36,000 difference. The example assumes the asset-level gain supports that recapture amount.
Bonus depreciation can increase section 1245 recapture at sale, so include that potential ordinary-income tax when evaluating the upfront deduction.
A 1031 exchange defers recognition and carries basis
A qualifying like-kind exchange can defer gain when real property held for business or investment is exchanged for qualifying replacement real property. Section 1031 generally no longer applies to personal property. Review the Form 8824 instructions before structuring the exchange.
Key requirements for a deferred exchange include:
- Identify replacement property in writing within 45 days after transferring the relinquished property.
- Receive the replacement property by the earlier of 180 days after transfer or the due date (with extensions) of the return for the year of transfer.
- Cash, non-like-kind property or certain net debt relief can cause current gain recognition, subject to the applicable limits and rules.
- Report the exchange on Form 8824 even when no gain is recognized.
- U.S. real property is not like-kind to foreign real property.
Replacement-property basis generally reflects carried-over basis with adjustments for additional consideration and any recognized gain. The exchange defers tax exposure rather than resetting the investment to a fresh fair-market-value basis.
Arrange the exchange before closing. Receipt of sale proceeds, related-party transactions and intermediary arrangements can affect qualification.
Certain qualifying DST interests may be used as replacement property; the structure is discussed in how to put property in a trust. Model taxes consistently when comparing investment IRR across exit options.
Other ways to reduce or defer the bill
Other options depend on the owner’s objectives, the type of gain and the transaction structure:
- Holding period: A holding period longer than one year can enable long-term treatment, subject to recapture and section 1231 rules. Short-term gains generally receive ordinary-income treatment.
- Installment sale: Eligible gain may be recognized as payments are received. Ordinary depreciation recapture is generally recognized in the sale year, and special ordering rules apply to unrecaptured section 1250 gain. Review the IRS installment-sale guidance when modeling seller financing.
- Qualified opportunity fund: The original deferral regime generally requires recognition by the end of 2026. The 2025 law created a new regime for qualifying investments beginning in 2027, including a rolling five-year deferral. The IRS’s 2026 announcement on new opportunity-zone designations explains the next designation cycle. Confirm the investment date, gain eligibility and the applicable 180-day period under section 1400Z-2 before relying on either regime.
- Losses: Capital-loss netting and, where applicable, the release of suspended passive losses on a fully taxable disposition can change taxable income. Their treatment depends on the loss category and disposition conditions.
- Basis at death: Qualifying inherited property generally receives a basis tied to its value at death under section 1014, which can reduce built-in gain. Estate inclusion and trust structure matter: Revenue Ruling 2023-2 addresses an irrevocable grantor trust whose assets were outside the owner’s gross estate.
- Charitable remainder trust: A qualifying CRT can sell contributed property and distribute an income stream under specialized rules. Beneficiary payments can carry out taxable income and gain. Review the IRS explanation of charitable remainder trusts with counsel before transferring an asset.
These approaches have different effects: some defer recognition, some change the taxable amount, and some depend on a charitable or estate-planning transfer. Evaluate both the current benefit and the later consequences.
When taxable gain arrives before cash
Investors in the original opportunity-zone regime need to plan for tax recognition even if their fund has not sold its property. IRS Notice 2026-40 confirms that qualifying investments held through the end of 2026 trigger inclusion of the remaining deferred gain in that tax year. The deemed included gain cannot simply be deferred again under the new regime, although an investment may retain eligibility for the separate benefit available after a qualifying ten-year hold.
For example, assume an investor must recognize $400,000 of remaining deferred gain in 2026 while the fund makes no distribution. The investor has taxable income without matching cash from the fund. The tax depends on the gain’s character and the investor’s circumstances. Sponsors should communicate anticipated distributions and reporting timing; investors should compare those cash flows with their applicable tax-payment dates before committing available cash elsewhere.
Who pays tax when a partnership owns the property?
A typical partnership-taxed syndication passes taxable results through to its partners. The amount distributed in cash can differ from taxable income allocated on Schedule K-1. IRS Publication 541 explains the partnership framework.
- Partnership or partnership-taxed LLC: Reports the sale and allocates taxable items to partners, retaining the required tax character.
- LP: Reports the allocated items using the investor’s applicable rates, loss limitations and state-tax and NIIT circumstances.
- GP: Reports allocations from its invested capital and promote, with applicable holding-period and carried-interest rules. Service fees are analyzed separately.
- Fund administrator or IR team: Coordinates records, distribution notices and tax-document delivery so investors can reconcile cash received with their tax reporting.
A waterfall distribution determines cash allocation under the agreement. Its label does not by itself determine the tax character reported on an investor’s K-1.
Preparing investor records for a property sale
Before closing, reconcile capital accounts, prior distributions, depreciation schedules and the sale statement with the tax preparer. Investors also need a clear schedule for receiving estimated tax information and final K-1s.
Agora’s investor reporting supports investor-specific statements and tax-document delivery. Keep those records aligned with the transaction’s tax work so investors can understand how the sale affects their investment.
Conclusion
A reliable exit-tax estimate starts with an adjusted basis and separates the relevant gain categories. In the worked example, $2.4 million of gain produces $626,200 of federal tax under the stated top-rate and NIIT assumptions.
Evaluate deferral options before closing, then calculate each partner’s allocation and expected reporting timeline. The same sale can produce different tax outcomes for different investors.
Explore Agora’s investor reporting tools for delivering statements and tax documents after a sale.